On closing day, plenty of homes that change hands around Katy, Pflugerville or the north side of San Antonio still carry a mortgage. Even so, nearly every Texas homeowner who calls me opens with the same worry: can you sell a house with a mortgage at all? To me, that says the mortgage payoff is one of the least explained steps in a Texas sale. I’ve watched that confusion cost sellers weeks of time and real money.
Can You Sell a House with a Mortgage in Texas?
Yes. Anyone telling you otherwise has the wrong picture of how a closing works.
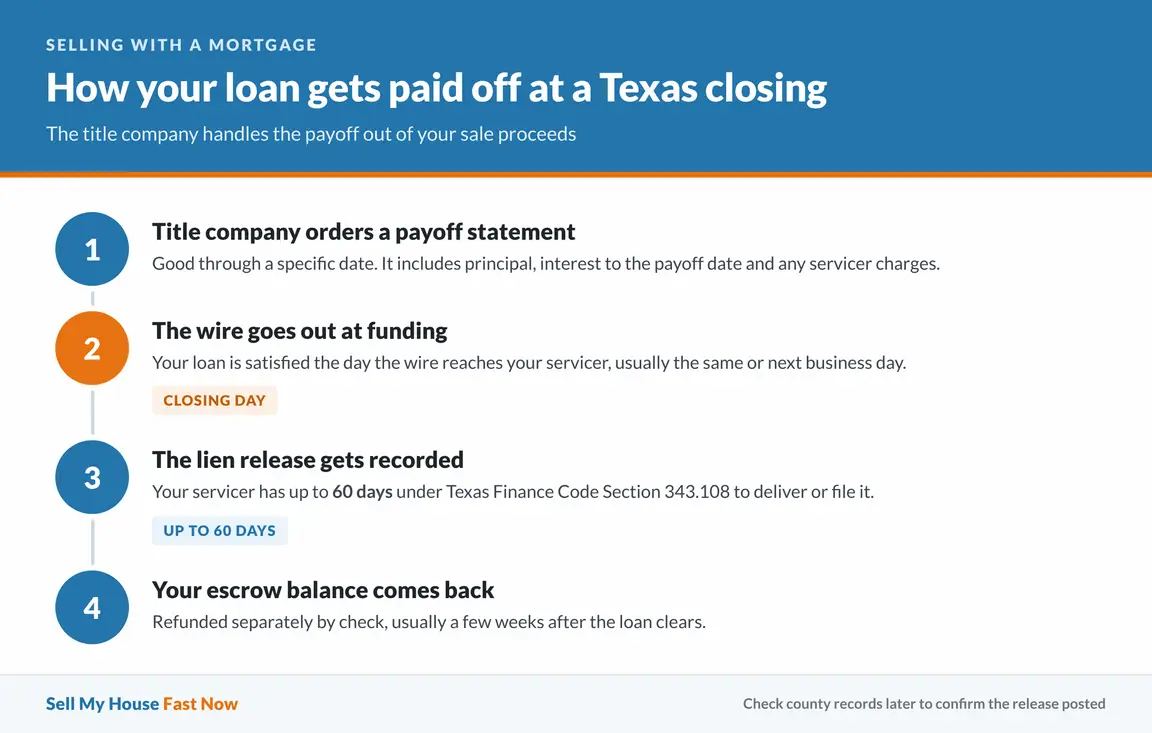
Your lender never owned your house. What the mortgage lender holds is a lien, recorded against the home at the county clerk’s office. When sale proceeds pay that lien off, the lender has to release it. The title company handles the mechanics behind the scenes. It orders a payoff statement, wires the lender its money at funding, then follows up so the release gets recorded.
Every month I meet folks who sat on a decision for a year, sure their loan balance had them stuck. It doesn’t work that way. You can sell a house with a mortgage in Texas the same week you decide to, as long as somebody’s ready to buy it.
Having a mortgage changes your math, not your permission. The mortgage payoff comes off the top of your sale price, and whatever remains after closing costs belongs to you. When the numbers work, you sell. If they come up short, you still have options, and I’ll walk through those further down.
A landlord I worked with up in Mesquite nearly talked himself out of selling a duplex he’d held there for nineteen years. He assumed the mortgage he still carried made a sale impossible. It didn’t, and his payoff came out of the proceeds at closing like it would in any other sale.
Texas sellers get a fairly clean process here, partly because title companies, not attorneys, run most closings in Texas. Their closers handle a mortgage payoff the way a mechanic handles an oil change.
Is It Hard to Sell a House with a Mortgage in Texas?
Title companies from Houston to El Paso pull payoff quotes from servicers every single business day. In a Texas sale, the friction usually comes from the market rather than from the mortgage.
That market has cooled. In October 2026, the Austin metro’s median sale price was $404,802, down nearly 7% from a year earlier, according to the Central Texas Housing Report. That same month, Houston’s single-family median slipped 3.0% to $320,000, per the Houston Association of Realtors. Each Texas metro moves on its own schedule, so the sales that matter for your price are the recent ones near your street.
Slow markets hit your wallet directly. Every extra week of showings means one more mortgage payment before you reach the closing table.
Where it does get harder is thin equity. Someone who bought in 2022 with a small down payment may not have enough cushion left to cover commissions. At that point the real obstacle is the gap between the payoff and the offer, not the loan itself.
Repair demands pile on, too. Pair a high loan balance with a house that needs work, and the usual listing route can turn into a slow bleed.
Some sellers in that spot call us at Sell My House Fast Now. A cash sale skips the appraisal and the repair haggling, which removes most of the back-and-forth. Listing still tends to net more when your house shows well and you can afford to wait out the days on market.
Lots of people sell a house with a mortgage in Texas every week without hitting any of these snags. The sellers who do hit one usually find it late, after a price is already set.
What Happens to Your Mortgage When You Sell Your Texas Home?
Sixty days. That’s the outer limit Texas Finance Code Section 343.108 gives your mortgage servicer once it receives the correct payoff amount. Within that window, it must deliver a release of lien to you or file it with the county clerk. You can shorten the wait. Send the servicer a written request on or before the 20th day after payoff. It then has to deliver or file the release no later than the 30th day after it gets your request.
Title companies request a payoff statement that’s good through a specific date. It covers principal and interest up to that day, plus any fees your servicer tacks on. At funding, the wire goes out and your mortgage is closed.
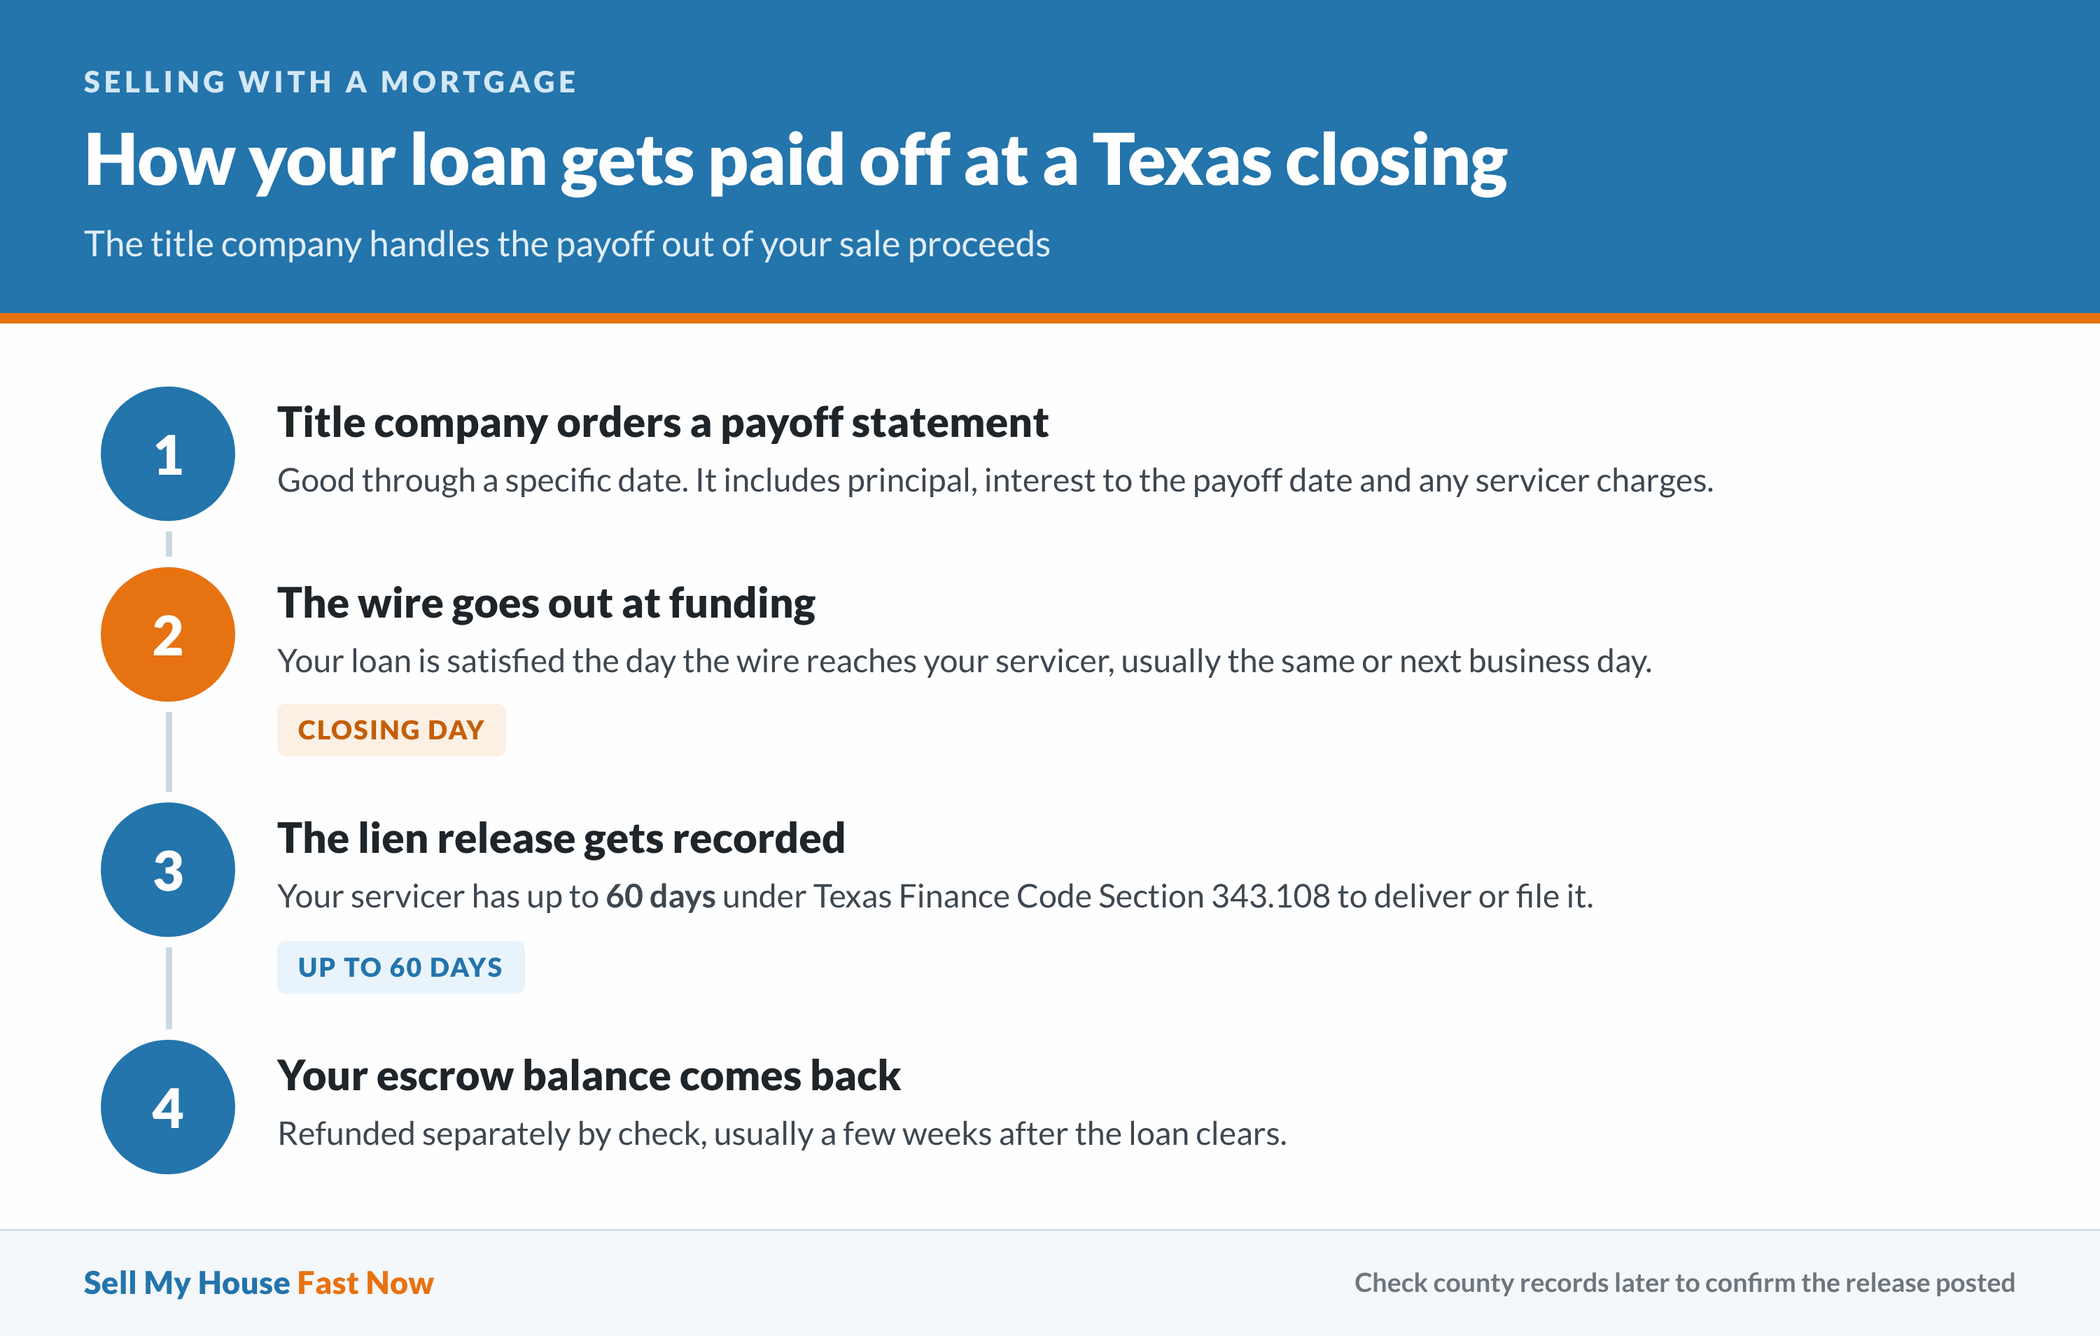
Escrow money is handled on its own track. Whatever sits in your escrow account for taxes and insurance isn’t part of the payoff. Servicers mail it back by check, usually a few weeks after the mortgage clears.
That recorded release deserves a second look. A deed of trust stays in the county records until the lien holder signs and records a release. Until that happens, every title search shows what looks like a live lien. In a normal sale, the title company tracks this for you. I’d still pull up your county’s records a couple of months later and make sure it posted.
Prepayment penalties are rare on conventional owner-occupied mortgages in Texas today, though hard-money and some portfolio loans still carry them. Read your promissory note before you list, just to be safe.
Do You Have to Tell Your Mortgage Lender You’re Selling?
Homeowners usually ask me this one on the same call, and the answer is no. Nothing obliges you to warn your lender before you list.
You could plant a sign in a Lubbock yard on Tuesday and sign a contract Friday without your servicer hearing a word.
Calling early still pays off, for a different reason. The balance in your app isn’t your mortgage payoff amount. Interest accrues daily. On top of that, the payoff quote carries charges the app never shows.
When equity is tight, the call matters even more. Get the real figure before you pick a list price.
Second mortgages, HELOCs and home improvement liens each need a payoff of their own. A line of credit also has to be formally closed rather than just paid down to zero. Skip that step, and the lender can leave its lien in place.
Outside of a short sale, loan assumptions are the one case where your lender has to be involved. Say you have an FHA or VA mortgage and a buyer wants to take it over at your old rate. The servicer then underwrites that buyer and has to approve the transfer. Texas buyers pay closer attention to assumable loans when today’s rates sit well above yours.
Outside of that, your mortgage lender is a vendor in this sale, not a gatekeeper.
What Happens to Your Home Equity When You Sell with a Mortgage?
Most people start by pulling up an online value estimate and subtracting the loan balance. They picture that difference landing in their bank account. What really shows up is smaller.
The gap between those two numbers is closing costs. In Texas they typically run somewhere between six and ten percent of your sale price when you list with an agent. Commissions take the largest share. The title policy, survey, escrow fees and any buyer concessions make up most of what’s left.
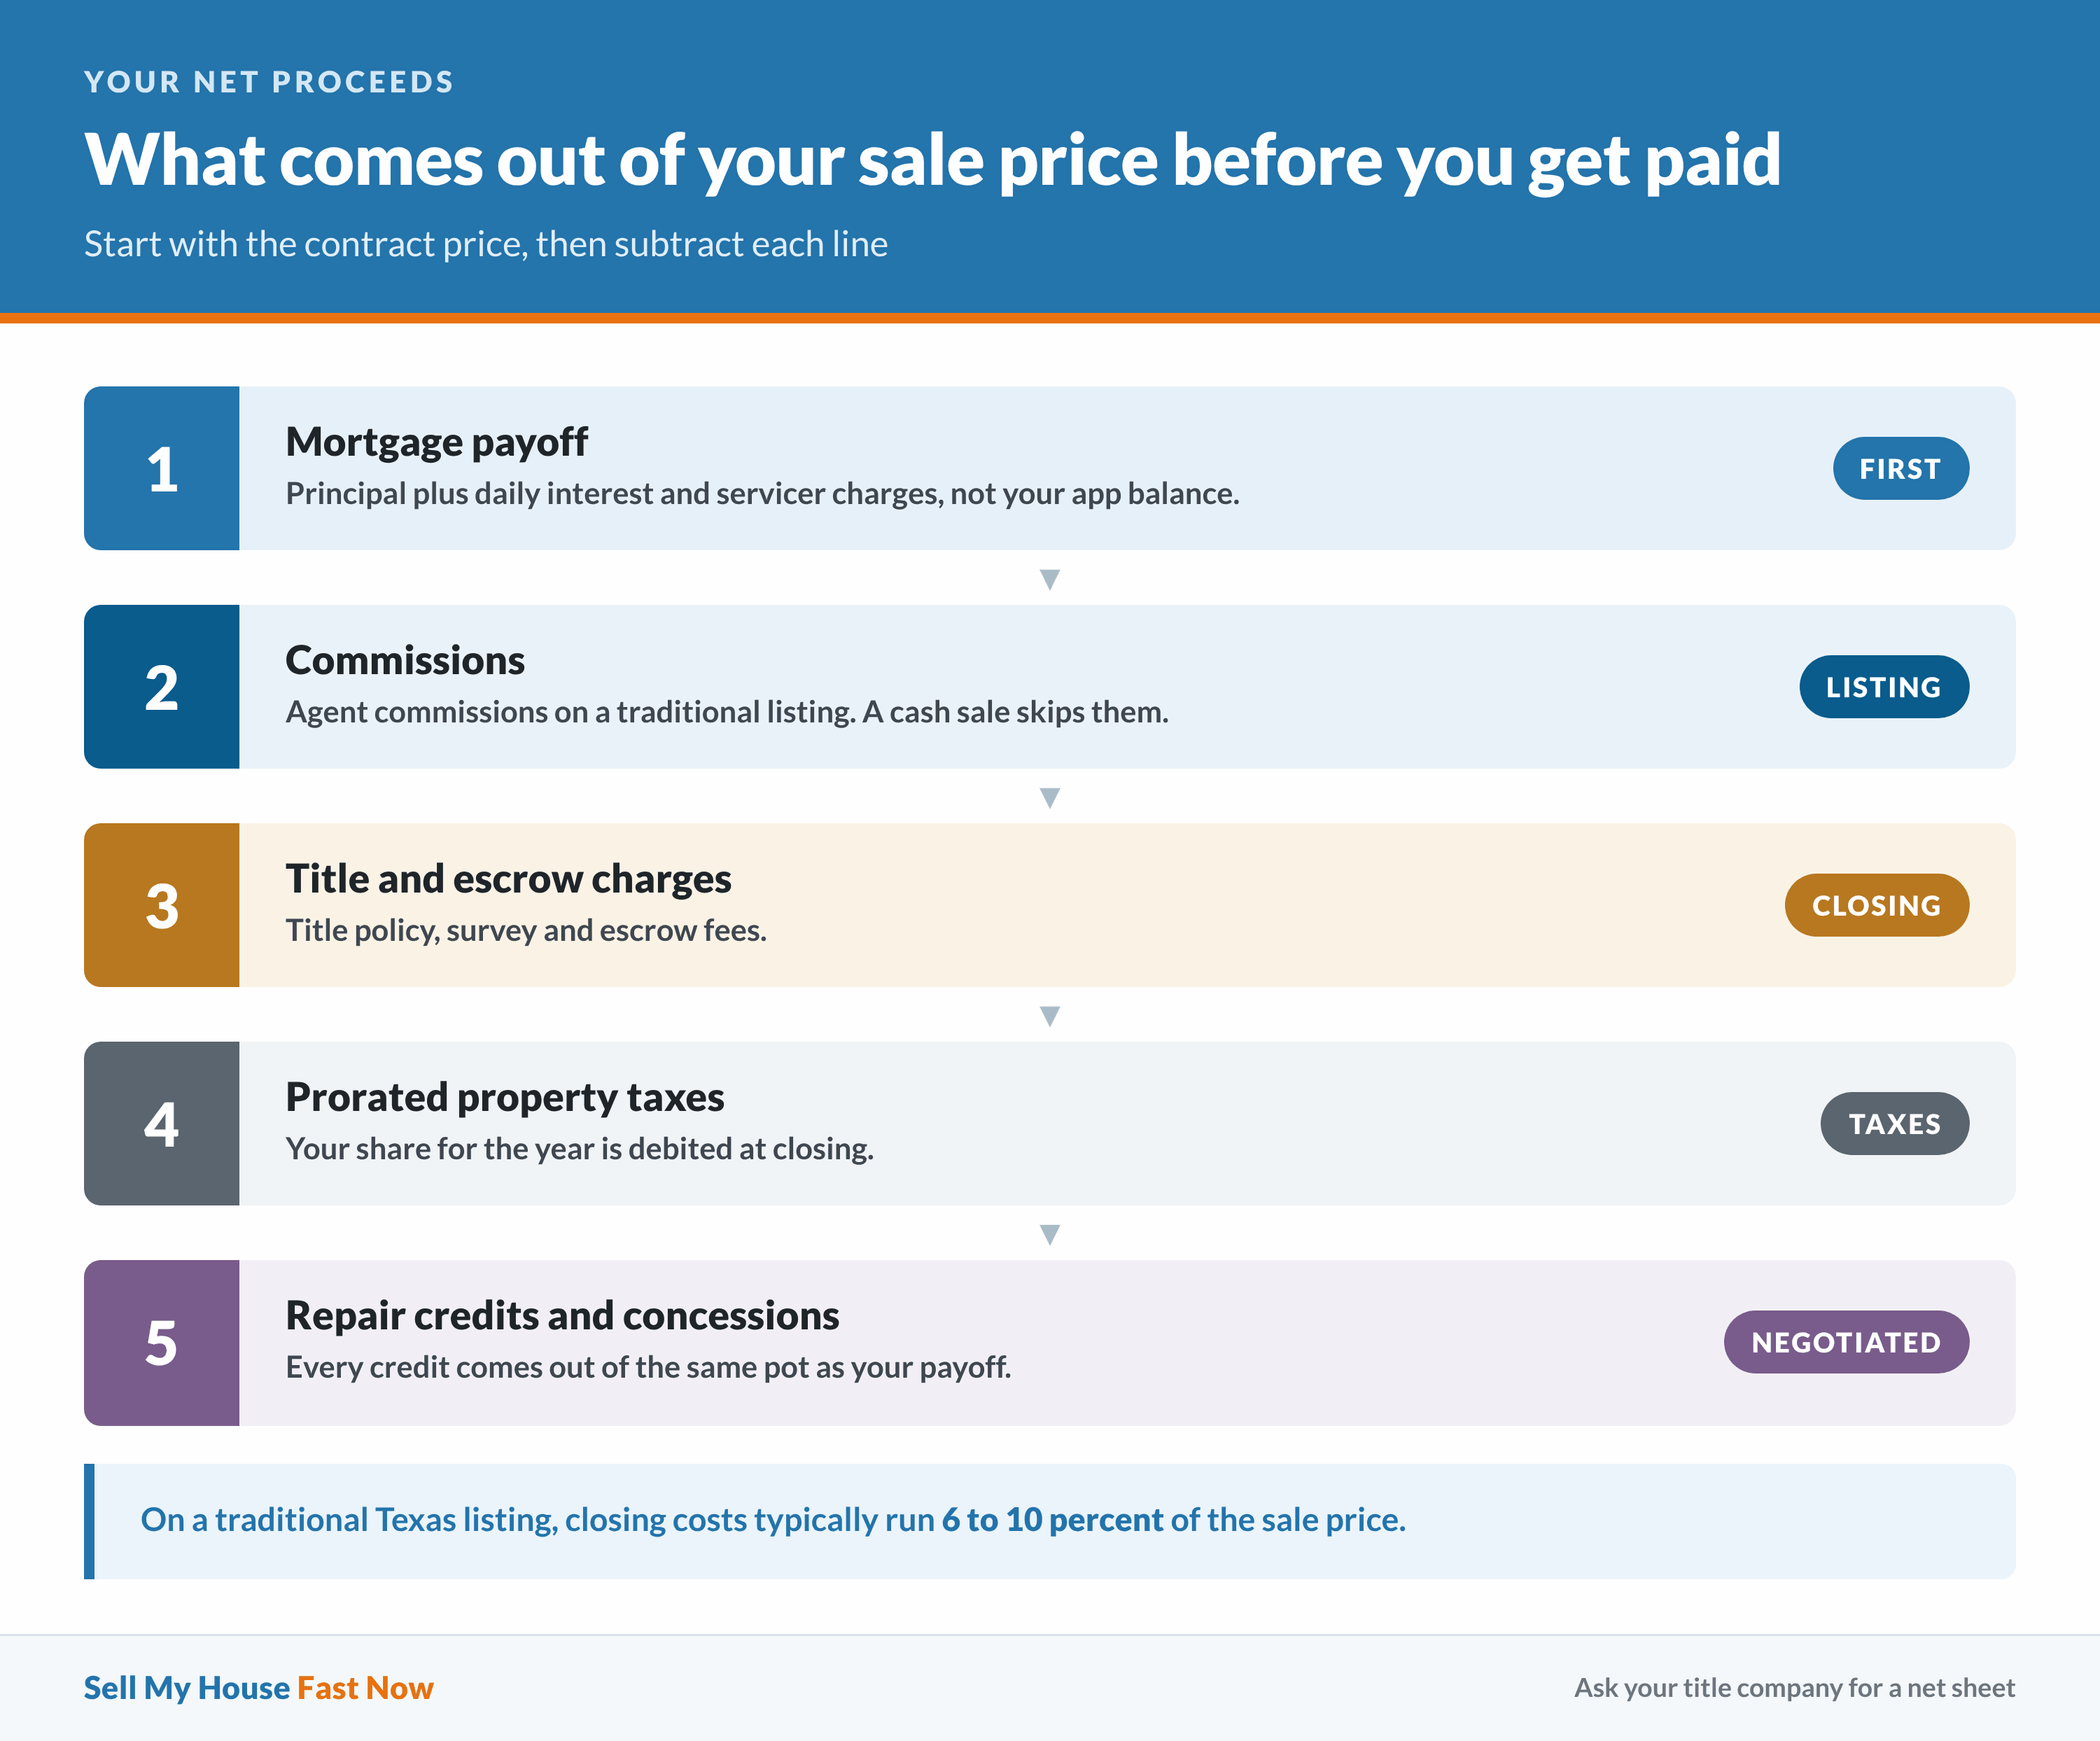
Property taxes add another wrinkle. With no state income tax, Texas leans hard on local property levies. At closing, you pay your prorated share for the year. Sell in November and you’ll likely credit the buyer for nearly eleven months of taxes, because Texas property tax bills usually don’t go delinquent until February of the following year.
In rising pockets of Fort Worth or Frisco, owners tend to assume their equity grew in a straight line. Early payments go mostly to interest, though. Five years in, a typical mortgage has barely touched the principal.
Federal tax is the last piece. Section 121 of the tax code shields much of your profit from it. You can exclude up to $250,000 of gain, or $500,000 if you file jointly. To qualify, you must have owned the home and lived in it as your main residence for at least two of the five years before the sale. The full rules are in IRS Topic 701.
If your Texas gain might top that cap, have a CPA run the numbers before you sign anything.
How Much Money Do You Get When You Sell a House with a Mortgage in Texas?
Get this figure wrong and you could sign a contract you can’t fund, then show up at closing owing the title company a check you never planned for.
Begin with the contract price, then subtract the mortgage payoff. Next come commissions, along with the title and escrow charges. Prorated property taxes and any repair credits you agreed to come off last.
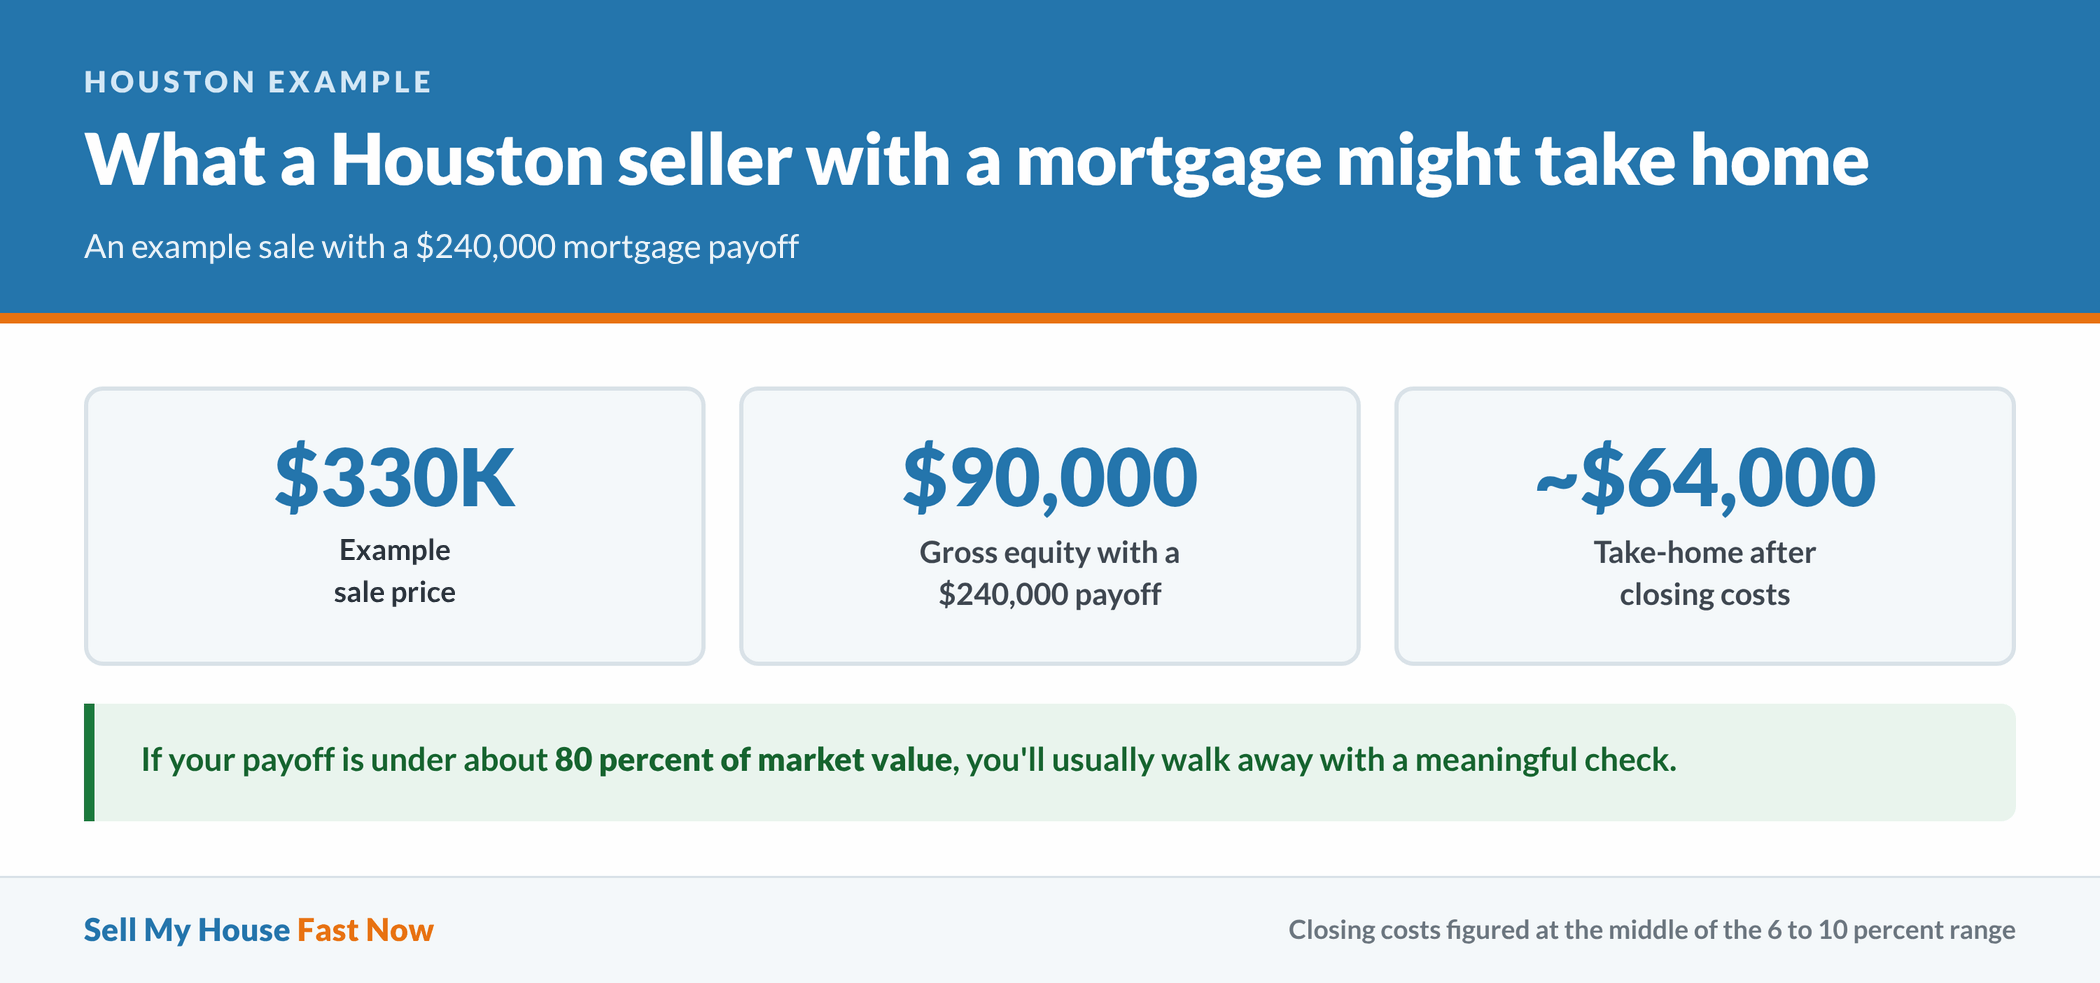
Put real numbers on a Houston house and it gets concrete. Say it sells for $330,000 with a $240,000 mortgage payoff, which leaves roughly $90,000 in gross equity. Take closing costs out at the middle of that six-to-ten range, and the take-home lands closer to $64,000.
Houston homes took an average of 59 days to sell in October 2026, unchanged from a year earlier, per that same Realtors report. Add thirty-odd days to close, and you’re covering roughly three more mortgage payments, plus insurance and utilities, before the wire lands.
Can you sell this way in Texas and still walk away with a real check? Usually you can, as long as your mortgage payoff sits under about eighty percent of market value.
Selling to a cash buyer moves the math in both directions. Commissions and repair credits drop out. The holding period shrinks to a couple of weeks, though a cash price usually lands below a retail listing. Some sellers come out ahead that way and plenty don’t. A seller’s net sheet for each option settles the question.
Many Texas title companies will draw one up at no charge if you ask.
What If You Owe More Than Your House Is Worth in Texas?
For years I figured negative equity was a 2008 problem Texas had left behind. The recent numbers proved me wrong.
ICE’s August 2026 Mortgage Monitor put San Antonio’s negative equity rate at 6.9% for the second quarter of 2026, with Austin close behind at 6.6%. Those two led every Texas market and ranked among the worst in the country. About 85% of underwater borrowers took out their mortgage in 2022 or later. Roughly three in four used a low-down-payment FHA or VA loan.
A buyer who put three and a half percent down near the peak in a Texas suburb could be upside down on that mortgage today.
You still have workable options. Bringing cash to closing is the cleanest one. You cover the shortfall from savings, the lien clears and your credit stays untouched. It stings, but it’s over.
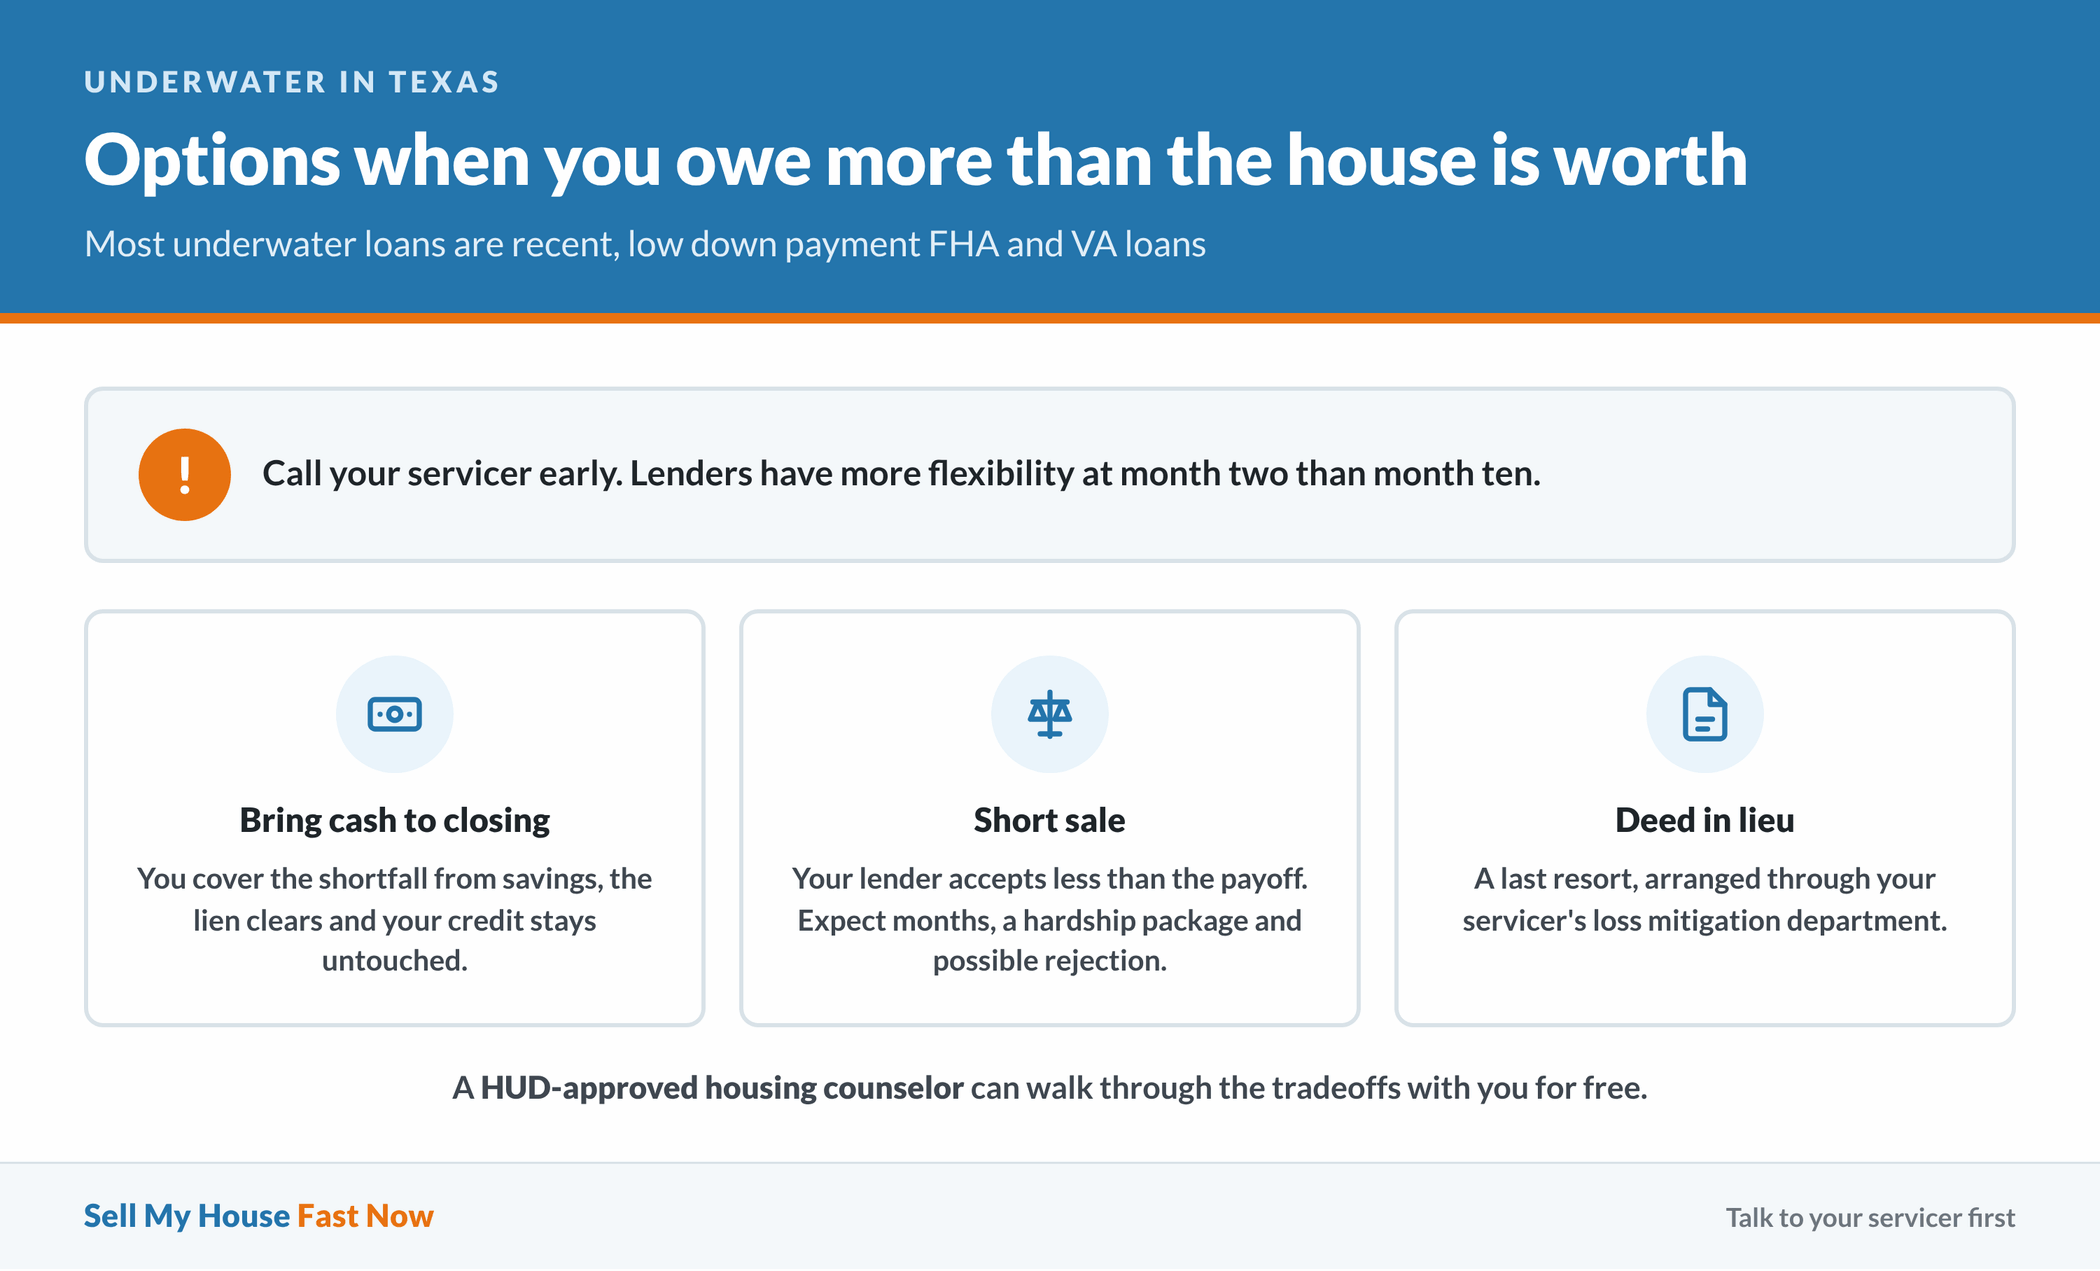
Next comes a short sale, where the mortgage lender accepts less than the full payoff and releases the lien anyway. These take months and need a hardship package. Even then, the bank can turn down your buyer’s offer after weeks of waiting.
Renting the house out until values recover is another route. Rent might cover some or all of the mortgage payment on a Texas house, though you take on landlord duties in the meantime.
A deed in lieu of foreclosure is the last resort, and you’d arrange it through your servicer’s loss mitigation team. For a second opinion, a HUD-approved housing counselor can help you weigh the tradeoffs at little or no cost. You’ll find the counselor directory on HUD’s site.
Lenders have far more room to help a borrower who calls in month two than one who calls in month ten.
What Are Common Mistakes People Make Selling a House with a Mortgage in Texas?
A seller I worked with in Tomball set her list price from the balance shown in her loan app. Three weeks into the contract, her mortgage payoff quote came back higher than she’d planned. She ended up renegotiating with her buyer from a weak spot.
The second mistake is canceling homeowners insurance the day you move out. Your mortgage lender expects coverage until the lien is released. A vacant house that catches fire between contract and closing turns into a mess for everyone.
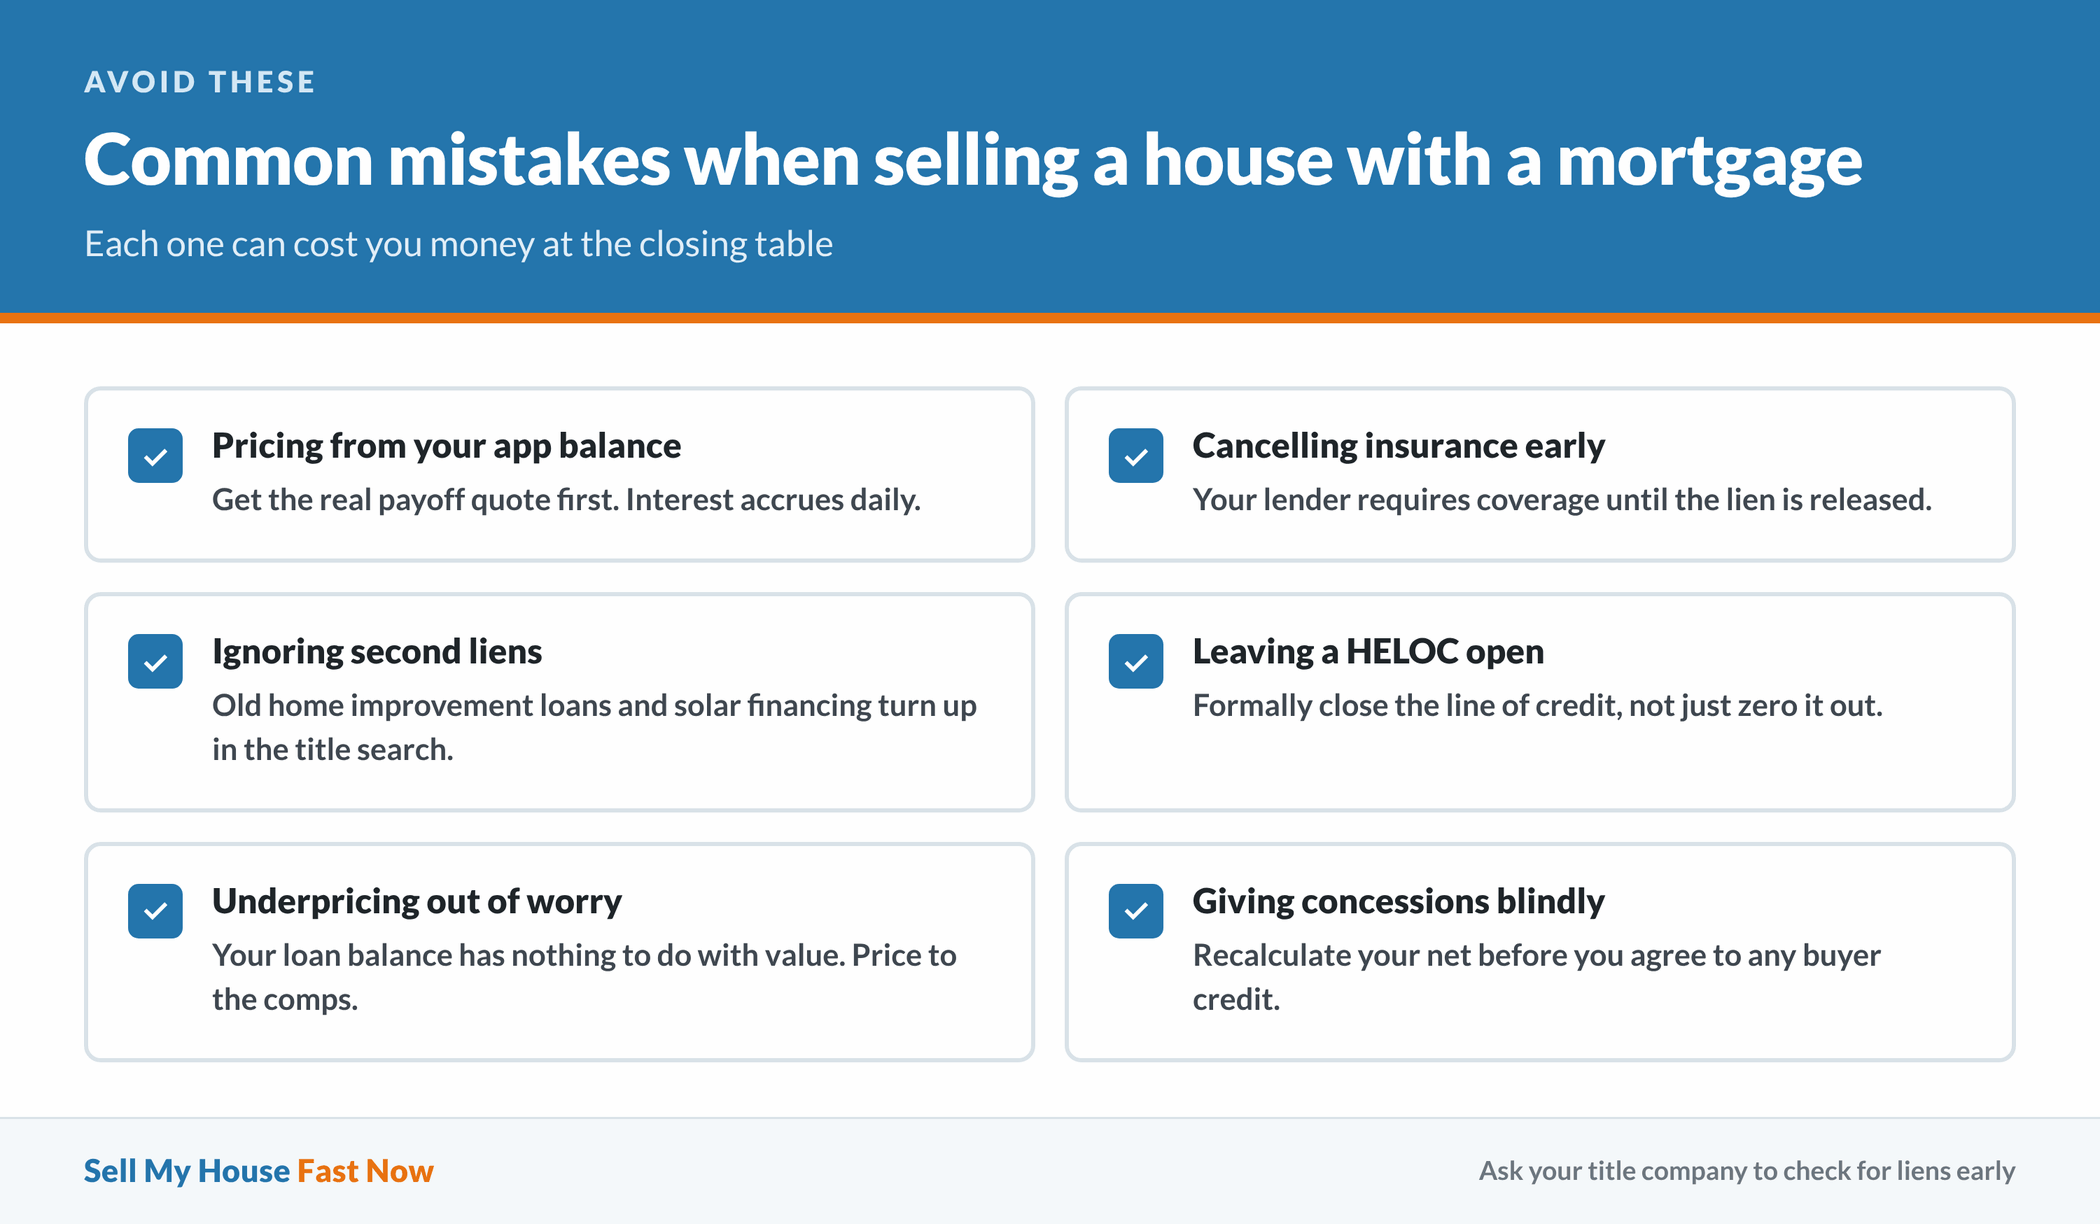
Third, and this one costs people real money: ignoring second liens until the title search turns them up. An old home improvement loan or a solar panel financing agreement can sit quietly in the county records for years. Find it two days before closing, and a smooth sale turns into a scramble.
A quieter error is underpricing out of worry about your loan balance. What you owe has nothing to do with what your property is worth. Nor will buyers across Texas pay more because your mortgage is big, or less because it’s small. Price to the comps.
One more I’d flag is agreeing to buyer concessions without rerunning your net. Every credit you hand across the table comes out of the same pot that pays off your mortgage. Even a few thousand here and there can push a thin-equity seller into bringing money to close.
Frequently Asked Questions About Selling a House with a Mortgage in Texas
Can I Sell a House with a Mortgage in Texas If I’m Behind on Payments?
Yes, and the sooner you act, the more choices you keep. As long as your sale proceeds cover the mortgage payoff, arrears included, the title company settles everything at closing and the lien gets released. Once a foreclosure sale date is posted, your window narrows fast. Call your servicer’s loss mitigation line before you list.
Does My Buyer’s Lender Care That I Still Have a Mortgage?
No. A buyer’s lender only cares about getting clear title at closing, and paying off your mortgage is exactly what delivers that. Underwriters don’t ask about the seller’s loan balance. The title commitment will list the payoff of your deed of trust as a Schedule C requirement, which the title company clears at funding.
How Long After Closing Does My Mortgage Disappear?
Legally, your mortgage is satisfied the day the wire reaches your servicer, usually the day of funding or the next business day. The recorded release takes longer, since the Texas deadline described earlier gives servicers a set window to deliver or file it. An online account may keep showing the loan for a week or two. It’s only a reporting lag, and it clears up on its own.
Will I Owe Taxes on the Profit When I Sell a House with a Mortgage in Texas?
Most homeowners owe nothing federally, thanks to the primary residence exclusion covered above, as long as you meet the ownership and use tests. Your mortgage balance plays no role in that math, because the IRS looks only at your gain over your adjusted basis. Texas has no state income tax, though a rental conversion or a second home changes the analysis enough to bring in a CPA.
What If My Spouse Is on the Mortgage but Not the Deed?
Community property rules apply in Texas, and they interact with homestead rights in ways that trip people up. In practice, your title company will almost always ask both spouses to sign the deed at closing, whoever’s name is on the mortgage or the title. Raise it with your closer early if you’re separated or mid-divorce, because that situation needs specific handling.
Can I Sell a House with a Mortgage in Texas That’s Currently Rented?
Yes, and the tenant doesn’t change how your mortgage payoff works, since the loan still gets paid from the sale proceeds at closing. What the lease changes is who can buy: an investor with a conventional investment loan can usually take it over and close on a normal timeline. A buyer who plans to live there needs the tenant out first, which adds another mortgage payment for every month you wait. Check your lease for early termination language and tell buyers about the occupancy from the first showing.
Is a Short Sale Better Than Letting the House Go to Foreclosure?
Generally yes, on the credit side and the human side alike. A short sale shows up as a settled mortgage debt rather than a foreclosure, and you control the timeline instead of a trustee’s sale schedule. The tradeoff is that your lender must approve the buyer and the price, which adds months and some uncertainty.
Do I Need an Agent to Sell a House with a Mortgage in Texas?
No. The title company handles your mortgage payoff and the lien release with or without an agent, even when a buyer and seller found each other directly. An agent earns the commission through pricing and negotiation, and that commission comes out of the same proceeds that pay off your loan. With thin equity, run your net with and without that fee.
What Happens to My Escrow Account If I Sell a House with a Mortgage in Texas?
Your escrow balance stays separate from the mortgage payoff and comes back to you by check from your servicer, usually within a few weeks of closing. Give the servicer your forwarding address before you move, since those checks do get lost in mail forwarding. If nothing shows up after about a month, call them directly.
How Fast Can I Close and Pay Off My Mortgage If I Need Out Quickly?
A cash sale can close in roughly two weeks in most Texas counties, limited mainly by how fast the title company can run the search and clear any exceptions. Your mortgage gets paid off at that closing, so a faster sale also means fewer monthly payments before the wire goes out. Financed sales take longer because appraisals and underwriting set the pace. When speed matters more than squeezing out the last few percent of value, that timing gap is the whole decision.
How Selling a House With a Mortgage Works in Dallas
Each day a house sits unsold adds interest to your payoff. Listings across Dallas-Fort Worth sat a median of 64 days in October 2026, a little longer than in September, according to Realtor.com data. We buy houses in Dallas with a mortgage still on them, and the title company pays your lender at closing like any other sale.
Find Out What You’d Walk Away With
If you’re weighing any of this, we’re glad to talk it through. We buy houses with mortgages still on them all over Texas. Tell us your payoff and what shape the house is in. From there, we’ll give you a straight read on whether listing or selling direct makes more sense for your timeline. You can reach us at Sell My House Fast Now any time. There’s no obligation, and no hard feelings if you go a different direction.
Have your latest mortgage statement handy and reach out to our team. We’ll ask for your address and a payoff estimate, then send a cash offer you can compare against listing. Fill out the form below whenever you’re ready.
Helpful Texas Blog Articles